What Is Index Investing, and Can It Get You Out Before 65?
Fund fee and performance figures verified as of October 2026. This is not financial advice. I’m a guy who got out, not a licensed advisor.
Index investing means buying one cheap fund that owns an entire slice of the market, like every company in the S&P 500, instead of trying to pick winners. For someone building walk-away money, it’s the most reliable way to grow the money you won’t need for the next few years, because it costs almost nothing and doesn’t require you to be smarter than the market.
That’s the whole answer. The rest of this is why it works, where it fits, and the one place people trying to leave early get it wrong.
Want your own number before you read on? The free worksheet works out how many months you need in about 10 minutes.
The Straight Answer
The Break Room Stock Picks
A few years after the Great Recession, the break room turned into a trading floor. Nobody was sure which way the economy was headed, and everybody had a theory.
One guy was betting on IBM. Big, safe, blue chip, the kind of name your dad would trust. Another was all in on pharma, specifically a small drug company called Nymox that he was sure had a winner in its pipeline. The third went the other direction entirely: commodities, on the bet that China was about to come roaring back and would need every ton of copper and barrel of oil it could get.
Nobody was buying our own company’s stock. We’d all sat through enough rounds of layoffs to know it was a sinking ship.
I didn’t say much. Mostly because I didn’t know anything. My own 401(k) was sitting in whatever the plan had defaulted me into years earlier, and I couldn’t have told you what I owned or what it cost.
Here’s how that year played out. IBM lagged the market. Commodities got crushed: oil collapsed, and copper slid as China slowed down instead of roaring back. And pharma? Health care was one of the best corners of the entire market that year. He picked the right sector.
He just picked the wrong stock. Late that year, Nymox announced its two big late stage trials had missed their main goals, and the stock lost more than 80% of its value in a day. In a year when the sector was a winner, he got wiped out.
So all three of them lost to the boring option, including the one who called the sector right. That’s what stuck with me. Being right about the big picture wasn’t enough. You also had to be right about the one company, the one trial, the one quarter. That’s not a plan. That’s a coin flip with a commission attached.
The real joke was on all of us. We were careful not to put a dime into the company stock, and every one of us still had our entire paycheck riding on it.
What Index Investing Actually Is
The SEC describes an index fund as a mutual fund or ETF that tries to match the returns of a market index, such as the S&P 500. You can’t buy an index directly. The fund buys the basket for you.
So instead of betting on IBM, or a basket of copper miners, or one drug trial, you own a sliver of hundreds or thousands of companies at once. When one blows up, it’s a rounding error. When the whole market rises over time, you rise with it.
That’s it. There’s no secret. The reason index investing works is mostly about what it removes: the guessing, the research analysts you’re paying for, and the fees that come with them.
Why Boring Wins: The Numbers Behind Index Investing
Professional fund managers with research teams and Bloomberg terminals are trying to beat the index every day. Most of them don’t.
S&P Dow Jones Indices tracks this in a report called SPIVA. In 2025, 79% of actively managed large cap U.S. stock funds trailed the S&P 500. In the first half of 2026, it was 67%. Those are full time professionals with research teams. Three guys with a newspaper and a hunch weren’t going to beat them.
Then there’s cost. According to the Investment Company Institute, the average index equity mutual fund charged 0.05% a year in 2025, while the average actively managed equity mutual fund charged 0.64%. Index equity ETFs averaged 0.14%.
A fraction of a percent sounds like nothing. It isn’t.
What a Fee Costs You in Runway
This is the math I wish someone had shown me at 30.
Say you invest $500 a month for 15 years. That’s $90,000 of your own money. Assume the market returns 7% a year before fees (an illustration, not a prediction; real returns jump around).
| Annual fee | Balance after 15 years |
|---|---|
| 0.05% (average index equity fund) | about $154,900 |
| 0.64% (average active equity fund) | about $147,700 |
| Difference | about $7,200 |
Now translate that into the only unit that matters on this site. If your household runs on $4,000 a month, that $7,200 is close to two months of runway. Two months of being able to say no, handed to a fund manager who probably didn’t beat the index anyway.
Run it on your own numbers: monthly contribution, years, and the fee difference between what you own and a cheap index fund. Any free compound interest calculator will do it in a minute. Then divide the gap by your monthly expenses. That’s how many months of freedom the fee is costing you.
Where Index Investing Fits in Your Escape Plan
This is where people who want out early make their first mistake. They hear “index funds win” and dump everything into the market.
Don’t. Order matters.
Money you might need in the next year or two, the money that covers you if you get walked out on a Tuesday, belongs in cash. I covered why in where to park walk-away money, and the accounts I’d actually use are in the best high yield savings accounts for your escape fund. Markets can drop hard and stay down. In my experience, the layoff rounds and the red screens tended to show up together, which is the worst possible time to be forced to sell.
Index investing is for the money behind that cash: the long term layer of your walk-away money that you won’t touch for five years or more. That’s the layer that compounds into real options.
The sequence I’d follow:
- Cash runway first, in a high yield savings account.
- Any 401(k) match your employer offers, because that’s part of your pay.
- Then index funds, in the accounts that fit your timeline.
The Account Matters If You Want Out Before 65
Here’s the part most “index investing for beginners” guides skip, because they assume you’re staying until 65.
Where you hold your index funds decides when you can touch them. Under IRS rules, money pulled from a 401(k) before age 59½ generally gets hit with a 10% additional tax on top of regular income tax, unless an exception applies. One exception: if you leave your employer in or after the year you turn 55, distributions from that employer’s plan may avoid the 10% tax. The rules have details and conditions, so read the IRS page and talk to a tax professional before you count on any of it.
I walked through what happens to that money when you’re let go in what happens to your 401(k) after a layoff.
A regular taxable brokerage account has no age rules. You pay tax on gains, but you can get to it whenever you need it. For someone planning an exit at 45 or 50, that flexibility is worth a lot. Most people who leave early end up with a mix: retirement accounts for the tax breaks, and a taxable account as the bridge.
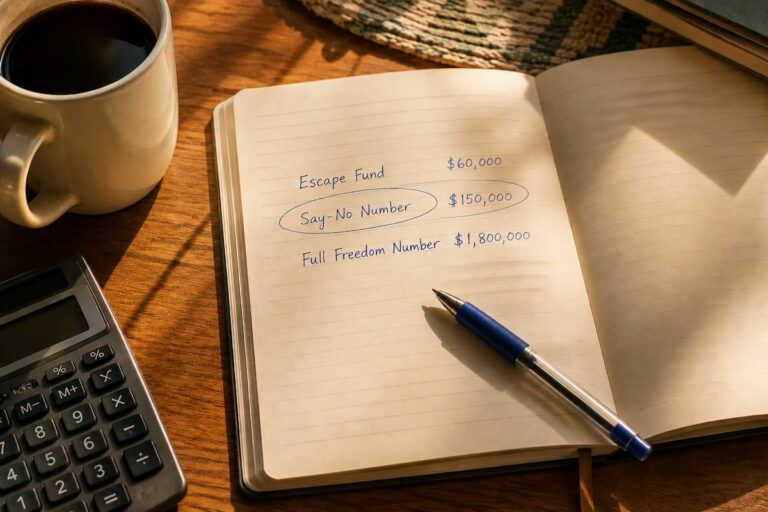
If you’ve already built enough that the retirement accounts can grow on their own, you may be closer to Coast FI than you think. And if you haven’t run your freedom number yet, do that first, because it tells you how big the index investing layer needs to get.
What Index Investing Won’t Do
It won’t make you rich fast. It won’t protect you from a crash; when the market drops 30%, your index fund drops about 30% too. And it won’t save you from yourself if you sell in a panic.
What it will do is take the guessing out, keep the fees from eating your runway, and let time do the heavy lifting. That’s not exciting. It’s not supposed to be. Excitement is what the break room had, and all three of those bets lost to the boring option.
Your One Move Today
Log in to your 401(k) or wherever your investments sit. For each fund, find the expense ratio. It’s on the fund fact sheet.
Then ask four plain questions:
- Is this fund tracking an index, or is someone picking stocks?
- What’s the expense ratio, and is there a cheaper index option in my plan?
- Am I holding a big chunk of my own employer’s stock?
- Is any money I might need in the next two years sitting in the market instead of cash?
If question 3 is yes, remember the break room. We were smart enough to stay out of the company stock and still had everything riding on the company through our paychecks. Don’t double that bet with your savings. Your job and your money shouldn’t be able to fail on the same day.
Frequently Asked Questions
Is index investing good for beginners?
Yes. Index investing for beginners is about as simple as investing gets: one low cost fund, broad diversification, and no stock picking. The main risk is market swings, so keep money you’ll need soon in cash.
How much money do I need to start index investing?
Many brokerages and index funds and ETFs have low or no minimums, and many 401(k) plans offer an index option. Starting small and consistent matters more than starting big.
Can I use index funds to retire early?
They’re a common core for early exits, but the account matters. Retirement accounts generally carry a 10% additional tax on withdrawals before 59½ unless an exception applies, so people leaving early often pair them with a taxable brokerage account. Check current IRS rules and get tax advice for your situation.
Index investing is the boring part of an exit, and boring is the point. I send a short weekly playbook on building walk-away money and using it to buy back your time. Join the list below and grab the Freedom Number worksheet.
Sources: SEC Investor.gov, Investor Bulletin: Index Funds · S&P Dow Jones Indices, SPIVA U.S. · ICI, Mutual Fund and ETF Fees, 2025 · IRS Topic 558 · Nymox Pharmaceutical filing, SEC EDGAR
This article is for education only and is not financial, tax, or investment advice. Your situation is your own; talk to a qualified professional before making investment decisions.