What’s the Best High-Yield Savings Account for Your Escape Fund?
The best account for your escape fund isn’t the one with the flashiest teaser rate. It’s the boring, liquid, FDIC-insured one you will actually leave alone. Below is what to look for, the account types that fit a walk-away fund, and the honest tradeoff between chasing the top rate and picking the one you will not touch.
The Straight Answer
This Money Has One Job, And It Isn’t Growth
Most “best HYSA” articles rank accounts by APY and stop there, as if a tenth of a percent is the thing standing between you and freedom. For the cash you set aside for your escape fund, it isn’t. This money has exactly one job: to be there, in full, the day you need it, no matter what the market is doing. That single reframe changes every choice that follows, because the moment you start optimizing this account for yield, you start making it a worse version of the thing it’s actually for.
In my own life, we use Ally Bank. Today it pays about 3% APY. It is not the highest rate on the market, but we have banked with them for years, there are no minimums and no fees, and getting to the money in an emergency has always been simple. Could we squeeze out a few more dollars by moving it? Probably. Will we? No, because the purpose of this money was never to buy our financial freedom. It is to buy us time if life throws everything at us at once and we need a runway to rebuild from a solid base.
The account matters less than starting before you spot the warning signs a layoff is coming.
What Actually Matters (And What Doesn’t)
Rank the criteria the way the job demands, not the way the rate tables do.
- FDIC insurance, no exceptions. Every dollar of runway must be federally insured, up to $250,000 per bank. This is not the place for anything clever.
- Liquidity. You need same-day or next-day access without penalty. No lockups, no CDs, no “we’ll mail a check in five business days” when you need it now.
- No gotcha minimums or fees. A high advertised rate that requires a $5,000 balance, or that quietly reverts after a promo window, isn’t a rate you can rely on. Look for no monthly fee and no minimum to earn the APY.
- Easy, fast transfers. How quickly can money move in from your paycheck and out to your checking the day you need it? Boring plumbing beats a flashy app.
- A rate that beats inflation-ish, then stop optimizing. Yield matters last. Any real HYSA pays roughly ten times the national average savings rate. Once you’re in that range, chasing the top tenth of a percent is rearranging deck chairs. On a $30,000 runway, the gap between 3.0% and 4.1% is about $330 a year, real money, but not freedom, and not worth moving the account you’ll actually leave alone.
Give It Its Own Account
The single most useful move is to keep this money in its own account, separate from everything else, and ideally at a different bank from your checking. Not because it needs a clever name, but because the separation does quiet work. Money that sits in your everyday checking is money you will spend, not because you’re careless, but because that is what checking accounts are for.
A separate savings account, one keystroke removed from your daily spending, is money you have to make a decision to touch. That small friction is a feature. It is the difference between an account you dip into for a vacation and one that is still whole the day your manager asks you to “hop on a quick call.” Keep it clearly apart from your everyday emergency fund, too, so each pot keeps its own job.
How Much Cash Belongs In It
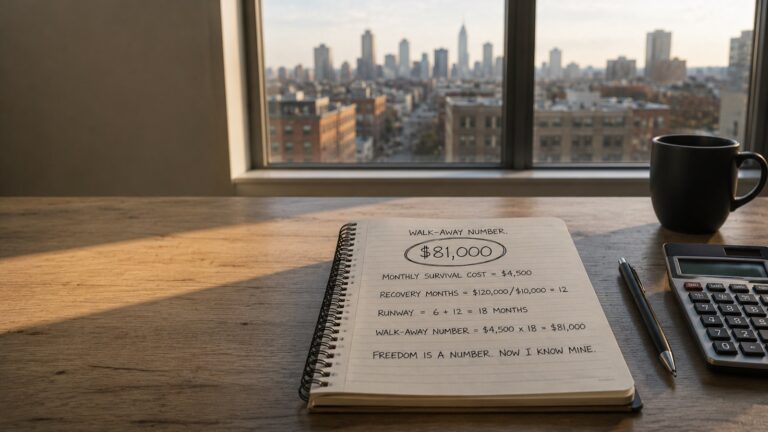
Here is where honesty matters, because not all of this has to sit in cash. Your emergency fund, the 3 to 6 months you might need same-day for a car, a medical bill, or a sudden gap, belongs here in full, because it has to be liquid the instant you reach for it. Your escape fund is a bigger, longer number, 12 to 18 months of survival expenses, and how much of it you keep in cash versus invest for growth is a real decision, one I break down in emergency fund vs escape fund. Personally, we keep our emergency fund in cash and invest the longer escape money, but that is a risk-tolerance call, not a rule. This is Number 1 of your Three Freedom Numbers; the one you can start funding tonight.
The rule for this account is simpler: whatever has to be there same-day, no matter what the market is doing, belongs in the HYSA. Whatever can ride out a bad year can live elsewhere. Either way, don’t let the size of the target stop you from opening the account. An empty perfect account earns you nothing. A funded good-enough one buys you the word “no.”
The Account Types That Fit (as of August 2026)
Here’s the honest landscape today. Rates move constantly, so treat these as a snapshot, not gospel, and check the current number before you open anything.
The one I use is Ally Online Savings, at about 3.00% APY, with no minimum, no monthly fee, and FDIC insurance. It is not the highest rate on this page, and I keep it anyway, for the reasons above: familiar, painless transfers, and an account I will never be tempted to move.
If you want the top rate and you’ll genuinely leave it alone, the higher-yield, still-FDIC-insured options right now include CIT Platinum Savings at around 4.10% APY (watch for any balance tier needed to earn the top rate), SoFi Checking and Savings at around 3.80% APY with no fees, and Marcus by Goldman Sachs at around 3.40% APY with no minimum and no fees, the plain-vanilla benchmark a lot of people default to. Verify every rate at the moment you open, because several carry promo windows or balance tiers.
The honest caveat: the “best” one for you is whichever you’ll actually fund and leave alone. A 4.1% account you keep raiding is worse than a 3.0% account you never touch. Pick for behavior first, rate second.
Your One Thing Tonight
Open one separate savings account tonight, at a different bank from your checking if you can, and seed it with $50 if that is all you have right now. Then automate a single recurring transfer into it the day after payday, so it builds without you thinking about it. Don’t overthink the bank. Pick an FDIC-insured account with no fees and easy transfers, fund it, and set the auto-transfer. The account you open tonight beats the perfect one you research for three weeks and never open.
Frequently Asked Questions
What’s the best high-yield savings account for an emergency or escape fund?
The best account is a boring, liquid, FDIC-insured savings account with no fees and no minimums that you’ll actually leave alone. Chase reliability and access first, and rate last. As of August 2026, solid options pay roughly 3% to 4.5% APY, versus a national average near 0.4%.
Is a high-yield savings account safe for my escape fund?
Yes, as long as it’s FDIC-insured (or NCUA-insured at a credit union), which covers up to $250,000 per bank. That insurance, plus instant liquidity, is exactly why cash in a HYSA beats investing money you may need on short notice.
Should I pick the account with the highest APY?
Not automatically. Once you’re earning several times the national average, the gap between the top rate and a slightly lower one is small in dollars and rarely worth the friction of moving. Pick the account you’ll fund and never raid, then stop optimizing.
The Account Matters Less Than The Habit
The people who build real runway aren’t the ones with the perfect APY. They’re the ones who opened the account and automated the transfer. I send a short weekly playbook on building your walk-away money faster. Join the list below and grab the Escape Fund worksheet.
Last updated: August 2026. Rates change frequently; confirm the current APY on the bank’s site before opening an account.
This is general information, not financial advice, and everyone’s situation is different. I only mention accounts I would use myself. Talk to a qualified financial professional before making decisions about your money.