How Much Should You Keep in Cash vs Invested When Layoffs Loom?
Figures verified as of October 2026. This is not financial or tax advice. It’s what worked for me after a lot of layoff rounds.
Keep enough cash to cover a realistic job search, then invest everything beyond that and treat it as untouchable. For a single person early in their career, 3 to 6 months of cash is usually enough; once you have dependents, a mortgage, or a specialized job, the cash vs invested split should lean closer to 12 months of cash.
That’s the answer. Here’s why I landed there, and it took two very different emergencies to get me to it.
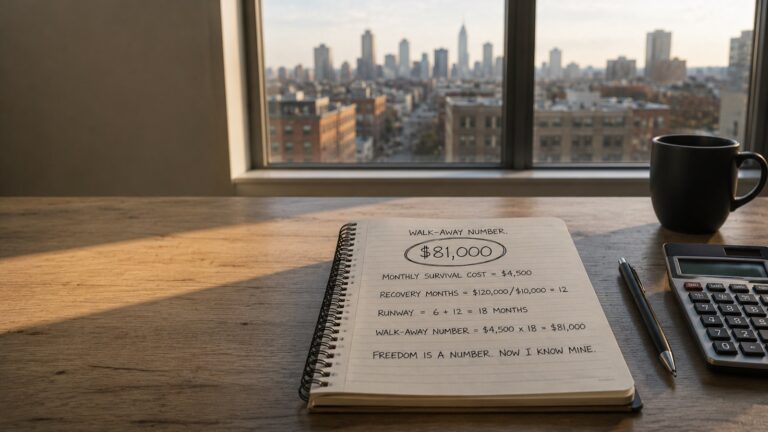
Want your own number before you read on? The free worksheet works out how many months you need in about 10 minutes.
The Straight Answer
The Month the AC Melted
Right after the Great Recession, my then girlfriend (now wife) and I bought a townhouse together. We were proud of ourselves. We’d scraped together an FHA down payment, and to get there, we emptied our emergency fund. Every dollar of cushion went into the house.
The next month was July. The AC unit died. Not a little broken. Melted. We put about $5,000 on a credit card to replace it, because there was nothing else to put it on.
Two weeks later, another round of layoffs hit.
I can still feel that one. A brand new mortgage, a fresh credit card balance, and a list being made somewhere in the building with names I couldn’t see. Zero cushion. I made it through that round, but I didn’t sleep much, and I don’t think I was very good at my job for a while either. Fear does that.
The Gap I Barely Remember
Fast forward years. By then I’d aggressively killed our consumer debt, kept 3 to 6 months of cash in reserve, and quietly built a regular brokerage account full of boring index funds.
Then I had a two month gap between jobs. I sold some of those investments to cover it.
Here’s the strange part: I barely remember it. No drama, no 3am math, no panic. It just didn’t register the way the AC month did. The money did its job, and I did mine, which was finding a new role at a better company instead of grabbing the first offer out of fear.
That’s the whole lesson, really. Same kind of shock. Completely different experience. The only thing that changed was the cushion. A cushion’s job isn’t to make you rich. Its job is to make the emergency boring.
Why 3 to 6 Months Stopped Being Enough
I picked 3 to 6 months in the first place for the same reason everyone does: it was the rule of thumb. Nobody ever explained where it came from.
As I got older, I stopped trusting it. Kids showed up. My role got more specialized, which paid better but also meant there were fewer jobs out there that matched both my skills and my income. A generalist can find a lateral move in a few weeks. A specialist can wait a long time for the right door to open.
The data backs that up. In the Bureau of Labor Statistics report for September 2026, 27.1% of unemployed people had been out of work for 27 weeks or longer. That’s more than six months. For more than a quarter of people looking, a 6 month fund wouldn’t have covered it.
And don’t count on severance to fill the gap. The Department of Labor is blunt about it: the Fair Labor Standards Act doesn’t require severance pay. It’s whatever the company offers or you negotiate. I’ve watched people walk out with one week per year of service, rounded down. If severance comes, treat it as a bonus and negotiate what you can. Don’t build your plan on it.
I also watched a coworker get laid off right before Christmas. Three young kids. His choice that week was to return the presents he’d already bought and get cheaper ones, or miss his mortgage payment. You tell me how that’s fair. It isn’t. But fair was never on the table. A cushion is the only thing that would have changed his December.
How to Set Your Cash vs Invested Split
This is how I’d set it today. It’s not a formula from a textbook, just the questions that would have saved me some sleep.
Start at 3 months of essential expenses. Then add 3 months for each of these that’s true for you, up to 12:
- Someone else depends on your paycheck (kids, a spouse, a parent).
- Your role is specialized enough that matching jobs are rare.
- You carry a mortgage or another big fixed bill you can’t shrink fast.
- Your household runs on one income, or on commission or bonus heavy pay.
A single 24 year old renter with a common skill set lands at 3 months. Me at mid career, with kids, a mortgage, and a specialized role, lands at 12. Most people land somewhere in between. If you want to go deeper on picking a number, I walked through it in 6 months of runway vs 12.
Everything above your cash number gets invested. That’s the cash vs invested split in one line: the cash covers the gap, the investments cover your future, and you don’t let one quietly eat the other.
What Goes in Each Bucket
The cash bucket goes somewhere boring, safe, and reachable in a day or two. For most people that’s a high yield savings account. I covered the tradeoffs in where to park walk-away money, and why this is bigger than a normal emergency fund in emergency fund vs escape fund.
The invested bucket goes into low cost index funds. I think of mine as untouchable money, not for a new car, not for a vacation, only for a real catastrophe. But it’s worth noticing that when my two month gap came, part of it was covered by selling from a regular brokerage account, not a 401(k). That account had no age rules on it. That flexibility is the second wall behind the first one.
Together, the two buckets are your walk-away money. One keeps you calm this year. The other keeps you from being trapped in ten.
What I’d Tell My 25 Year Old Self
Keep 3 to 6 months when you’re single and starting out. Then build toward a year as you approach 30, because life gets complicated: relationships, kids, bigger roles that are harder to replace at the same pay.
Kill consumer debt first. We pay our cards off in full every month, no exceptions, and I covered the order of operations in which debt to kill first. We’re also paying our mortgage off early, even though a spreadsheet says we’d probably come out ahead investing that money instead. I’ve made peace with that. Life doesn’t work like a math problem, and you can’t put a price on not being trapped.
And I’d lean harder into a regular, after tax brokerage account in my twenties instead of pushing every spare dollar into the 401(k) to save on taxes. My income then doesn’t hold a candle to my income now, so the tax break I was chasing was small. The buffer I gave up would have done wonders for my mental health. (Still take any employer match. That’s part of your pay. And talk to a tax professional about your own situation.)
Your One Move Today
Divide the cash you could reach this week by your essential monthly expenses. That’s how many months of cushion you have right now.
Then run the four questions above and get your target. The gap between the two numbers is your next savings goal. Anything you’ve got above the target can go to work in the invested bucket.
Frequently Asked Questions
How much cash vs invested should I have if I’m worried about layoffs?
Keep enough cash to cover a realistic job search, often 3 to 6 months for single people early in their careers and closer to 12 months for people with dependents, a mortgage, or a specialized role. Invest money above that target for the long term.
Should I count severance as part of my emergency fund?
I wouldn’t. Federal law doesn’t require severance pay, so it depends entirely on your employer or what you negotiate. Treat it as a bonus if it comes.
Is it okay to sell investments to cover a job gap?
It can be, especially from a regular taxable brokerage account that has no age restrictions. Selling from retirement accounts can trigger taxes and penalties, so check the rules and get advice first. Ideally, cash covers the gap and investments are the backup.
The right cash vs invested split won’t make the next layoff round fair. It just makes it survivable. I send a short weekly playbook on building walk-away money and using it to buy back your time. Join the list below and grab the Freedom Number worksheet.
Sources: U.S. Bureau of Labor Statistics, The Employment Situation, September 2026 · U.S. Department of Labor, Severance Pay
This article is for education only and is not financial, tax, or investment advice. Your situation is your own; talk to a qualified professional before making decisions about your money.