How Much Money Do You Need to Quit Your Job? (Real Examples)
How much money do you need to quit your job? Less than most people assume, and it depends on your life, not a generic seven-figure target. Below are the three freedom numbers, the Escape Fund, the Say-No Number, and the Full Freedom Number, run for four real situations, so you can find the one closest to yours and see roughly where you stand.
Run your own numbers as you read. The free worksheet does the math in 10 minutes.
The Real Answer
Your number isn’t the internet’s number
Every “you need $X million to retire” headline is answering a question you didn’t ask. They’re describing the biggest, slowest version of freedom, built for an average that isn’t you. Your real number is driven by one thing the headlines ignore: your expenses. Two people earning the same salary can need wildly different amounts to walk away, because one spends half what the other does.
For me, seeing this was a huge relief. I was deep in the 9-to-5 grind with no end in sight, and realizing the first number was reachable, and far closer than the retire-forever figure, was the moment the whole thing shifted from hopeless to possible. It wasn’t the finish line. It was a starting point, the place where life could start getting easier. I hope it reframes it for you too.
So instead of preaching, let me just show you. Four lives, three numbers each, real math.
A 20-second refresher on the three numbers
If you haven’t run yours yet, start with what’s your freedom number. Here’s the short version we’ll use for every scenario below:
- Escape Fund: your runway. Roughly 12 to 18 months of stripped-down survival expenses, in cash. Buys you the word “no” this year.
- Say-No Number: close to what the FIRE community calls Barista FIRE, the amount invested where you can trade the high-stress job for an easier one. Take your annual expenses, subtract the income you’d happily earn from lower-stress work, and multiply the difference by 25.
- Full Freedom Number: annual expenses times 25. Never need to work again. This is the classic FIRE number, short for Financial Independence, Retire Early.
Scenario 1: The single renter
Priya, 29, rents, no dependents. She spends about $42,000 a year ($3,500 a month), and if she lost her job and stripped her expenses to the bone, she could survive on roughly $2,600 a month.
- Escape Fund: about $32,000 to $47,000 (12 to 18 months of survival expenses).
- Say-No Number: she’d happily earn $30,000 doing lower-stress work. $42,000 minus $30,000 = $12,000 gap, times 25 = $300,000.
- Full Freedom Number: $42,000 times 25 = $1,050,000.
Takeaway: her Say-No Number ($300k) is less than a third of her full number. She can downshift to a calmer job decades before she’s “done.”
Scenario 2: The family of four
The Reyes family. Two kids, a mortgage, one and a half incomes. They spend about $90,000 a year ($7,500 a month); bare-bones, they could hold at $6,000 a month.
- Escape Fund: about $72,000 to $108,000 (12 to 18 months at survival expenses).
- Say-No Number: if one parent shifted to $50,000 of lower-stress work, the gap is $90,000 minus $50,000 = $40,000, times 25 = $1,000,000.
- Full Freedom Number: $90,000 times 25 = $2,250,000.
Takeaway: bigger life, bigger numbers, but the same shape. The Say-No Number is still under half the full number, and the Escape Fund is a two-to-three-year goal, not a fantasy.
Scenario 3: The high earner in golden handcuffs
Dominic, 41, big title, big comp, big spending. He spends about $150,000 a year ($12,500 a month). Trimmed hard, he could get to $8,000 a month.
- Escape Fund: about $96,000 to $144,000.
- Say-No Number: an easier job he’d take pays $80,000. Gap is $150,000 minus $80,000 = $70,000, times 25 = $1,750,000.
- Full Freedom Number: $150,000 times 25 = $3,750,000.
Takeaway: the trap of the golden handcuffs is visible right here. His high spending makes every number enormous. The single most powerful move he can make isn’t earning more, it’s cutting expenses, because every dollar he stops spending lowers all three numbers by $25.
Scenario 4: The low-cost-of-living life
Sam, 34, deliberately lean, lower-cost area, few fixed costs. They spend about $30,000 a year ($2,500 a month), and could hold near $2,000 a month.
- Escape Fund: about $24,000 to $36,000.
- Say-No Number: happy earning $22,000 from part-time or passion work. Gap is $30,000 minus $22,000 = $8,000, times 25 = $200,000.
- Full Freedom Number: $30,000 times 25 = $750,000.
Takeaway: the quietest superpower in the whole article. Sam needs a fifth of what Dominic needs for the same freedom, not because they earn more, but because they need less. A $200,000 Say-No Number is reachable in a normal working life.
What the four scenarios reveal
Three things jump out when you line them up.
First, your numbers are driven by your expenses, not your income. Dominic earns far more than Sam and needs five times as much to be free. Spending is the dial.
Second, the Say-No Number is always the closest door. In every scenario it’s under half the full FIRE number, and it’s the one that lets you trade the job that’s hurting you for one that isn’t, years before the big number arrives.
Third, the Escape Fund is closer than any of it, a one-to-three-year goal that buys you real leverage now. Size it with your walk-away money.
(Markets don’t return a smooth number, so treat every figure here as an illustration, not a promise.)
Your one thing tonight
Find the scenario closest to your life, then run your own. You need three inputs: your real annual expenses, the income you’d happily earn from easier work, and your stripped-down survival number.
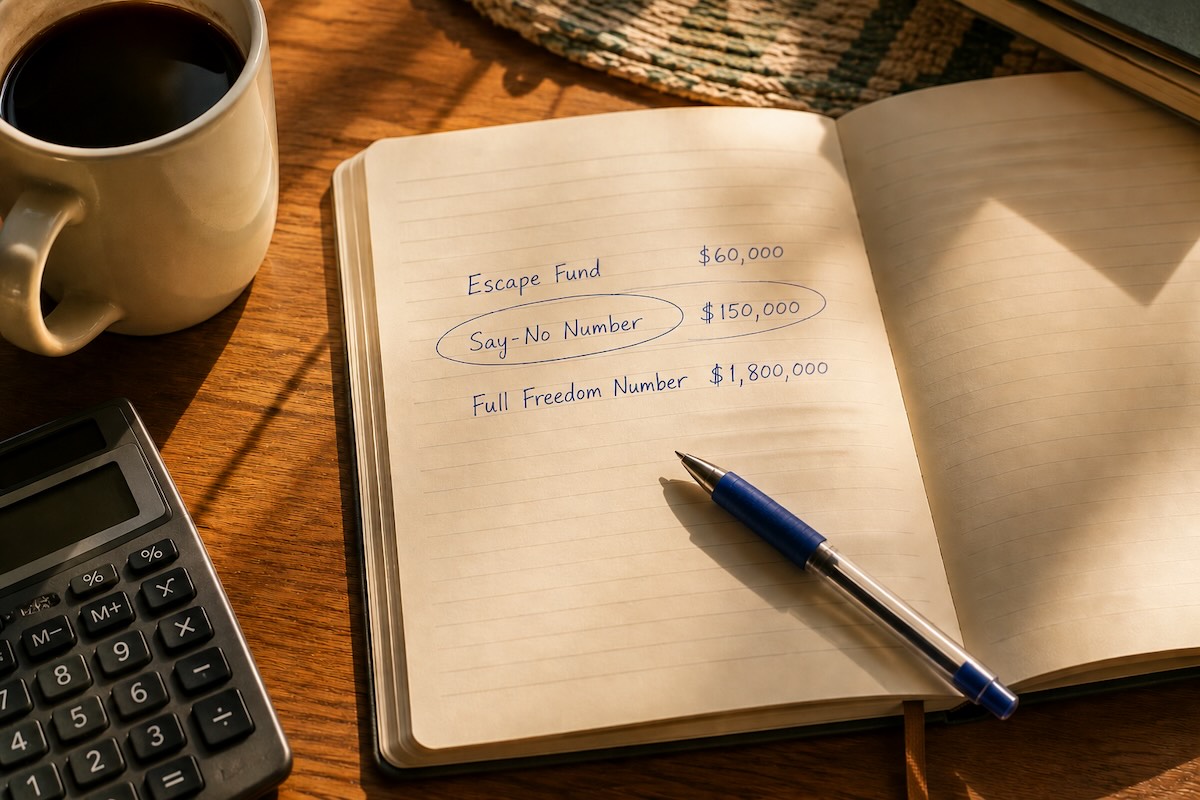
Escape Fund is 12 to 18 months of survival costs. Say-No Number is (expenses minus easier income) times 25. Full Freedom Number is expenses times 25. Do the arithmetic once, write the three figures down, and circle the Say-No Number, because that’s usually the first real door out. Grab the Freedom Number worksheet below to run all three in ten minutes.
Frequently asked questions
How much money do you need to quit your job?
It depends almost entirely on your expenses, not your income. A realistic first target is your Say-No Number, your annual expenses minus the income you’d happily earn from lower-stress work, times 25, which is often a fraction of the full “retire forever” number. In the examples above it ranged from about $200,000 to $1.75 million.
Do I need a million dollars to quit my job?
Usually not, at least not to downshift. Full financial independence can run seven figures, but the Say-No Number, the point where you can leave a toxic job for an easier one, is frequently in the low-to-mid six figures, and your Escape Fund runway is smaller still. You need less than the headlines say.
How do I calculate my own number?
Start from your annual expenses. Multiply by 25 for full freedom, subtract an easier income before multiplying for your Say-No Number, and set aside 12 to 18 months of survival costs as your Escape Fund. Same three numbers, your real figures.
The number that keeps you stuck is usually someone else’s
The number that keeps you stuck is almost always someone else’s number. Once you run your own, the exit stops being a fantasy and becomes a figure with a deadline. I send a short weekly playbook on hitting these numbers faster. Join the list below and grab the Freedom Number worksheet.
This is general information, not financial advice. The names and figures here are illustrations to help you run your own numbers, not recommendations for your situation, and investment returns are never guaranteed. Talk to a qualified financial professional before making decisions about your money.